VC & PE Fund Distribution Waterfall: Carried Interest, Catch-Up & Clawback (Excel)
Originally published: 14/09/2026 09:11
Publication number: ELQ-75033-1
View all versions & Certificate
certified

VC & PE Fund Distribution Waterfall: Carried Interest, Catch-Up & Clawback (Excel)

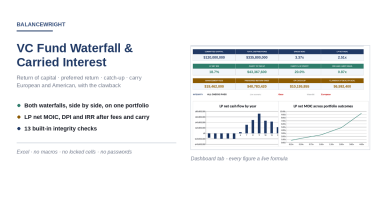
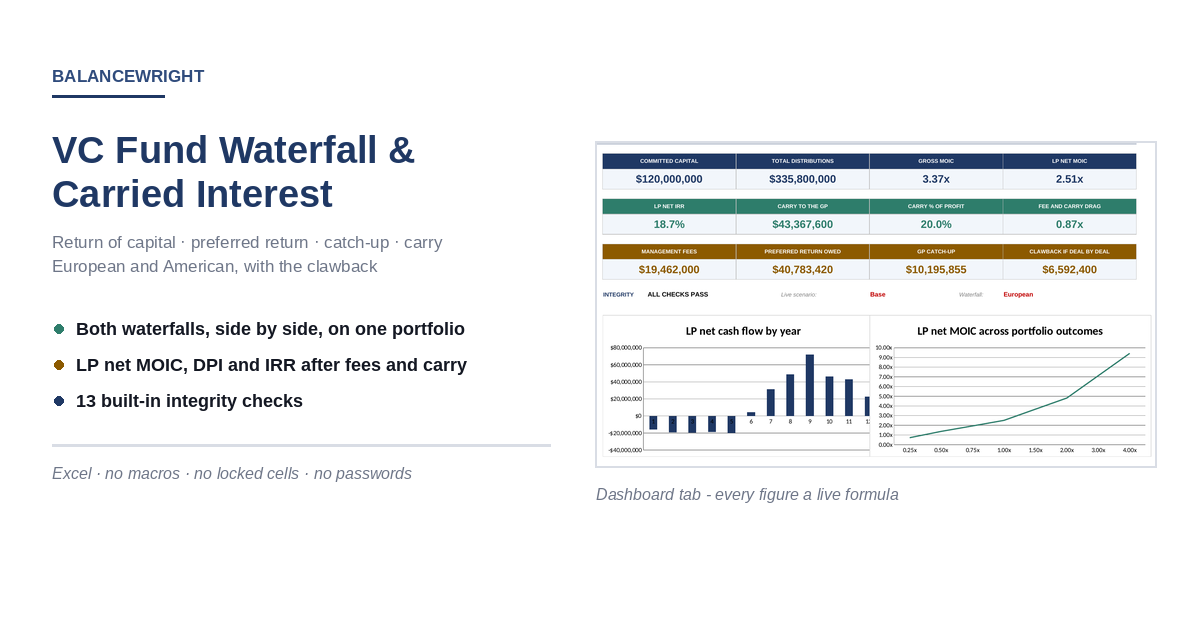
Whole-of-fund European waterfall tier by tier: exact GP catch-up, the deal-by-deal American comparison, and the clawback the GP owes back.

Description
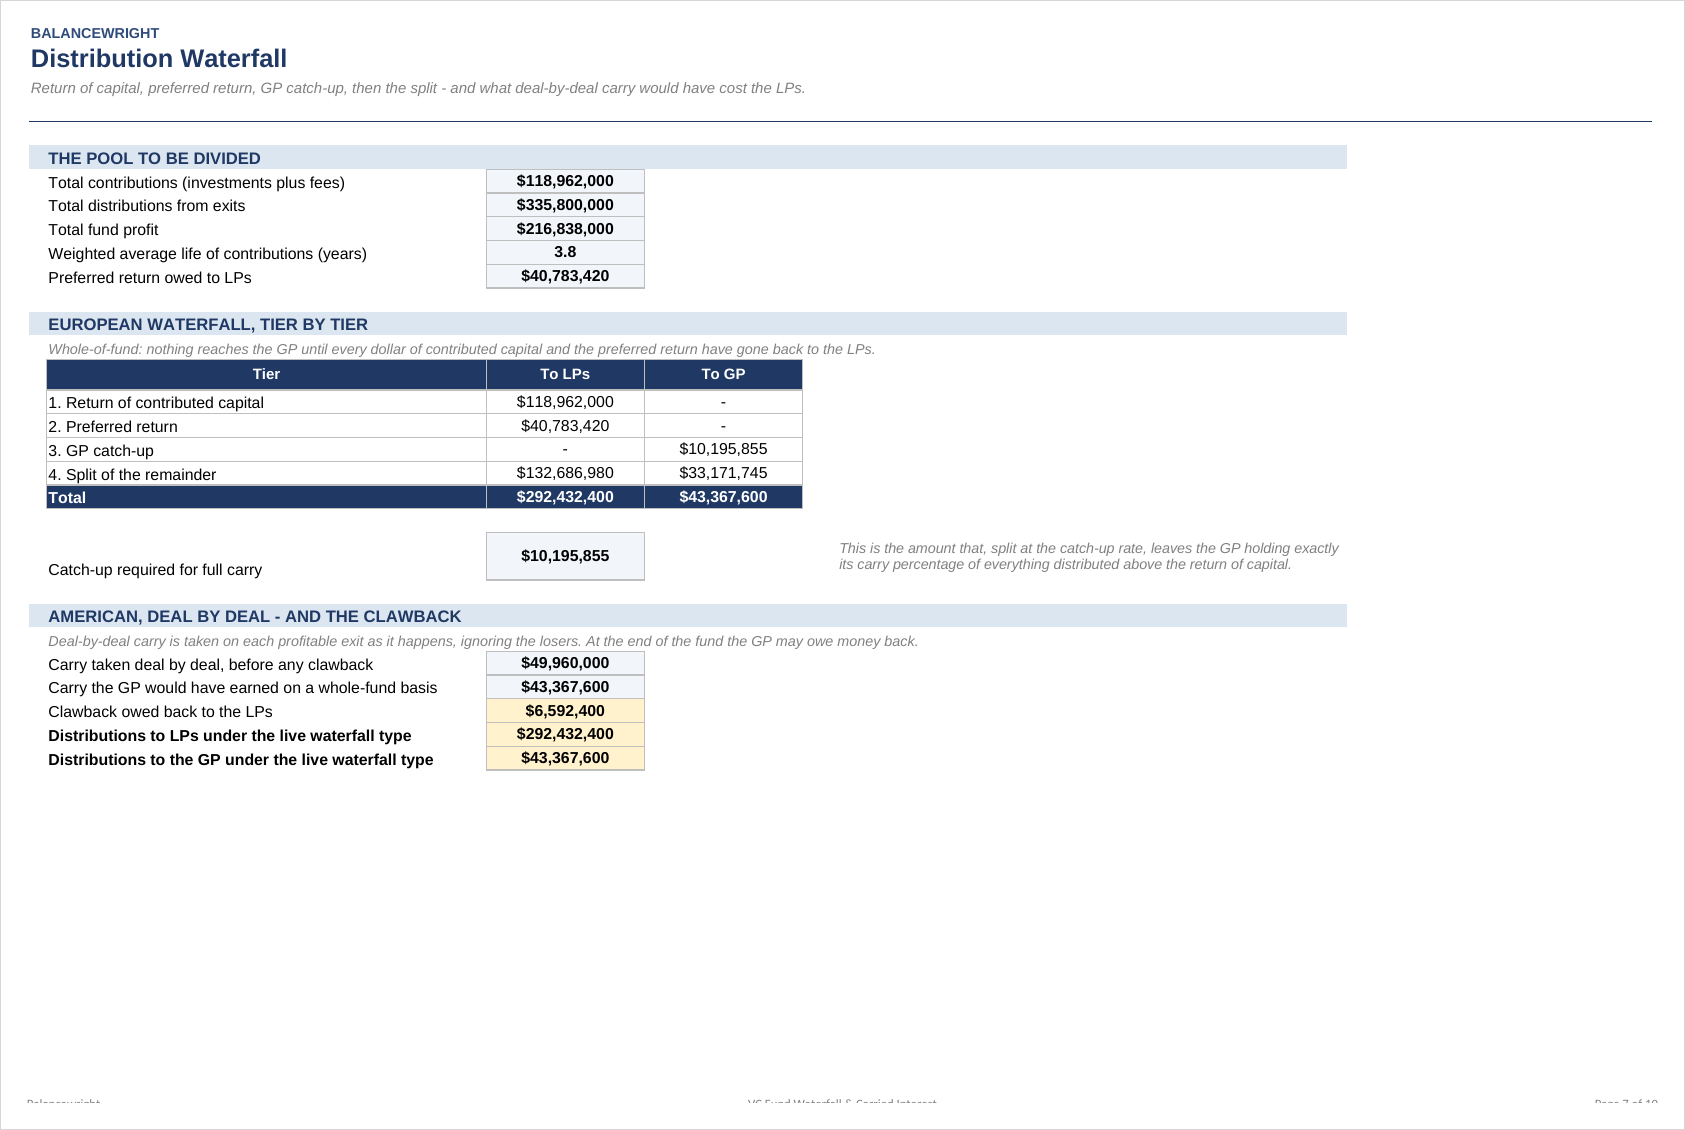
A European waterfall pays out in order. First the LPs get every dollar of contributed capital back - not just the money that went into companies, but the management fees too. Then they receive the preferred return, compounded on that capital. Only then does the GP see anything.

The third tier is the one that surprises people. The catch-up exists so that, once the LPs have their preferred return, the GP is brought up to its full carry percentage of everything distributed above the return of capital, as though the hurdle had never applied. At a hundred percent catch-up rate the GP takes every dollar in that band. This model computes the exact catch-up amount rather than approximating it, and an integrity check confirms the GP never ends up past its headline percentage of fund profit.

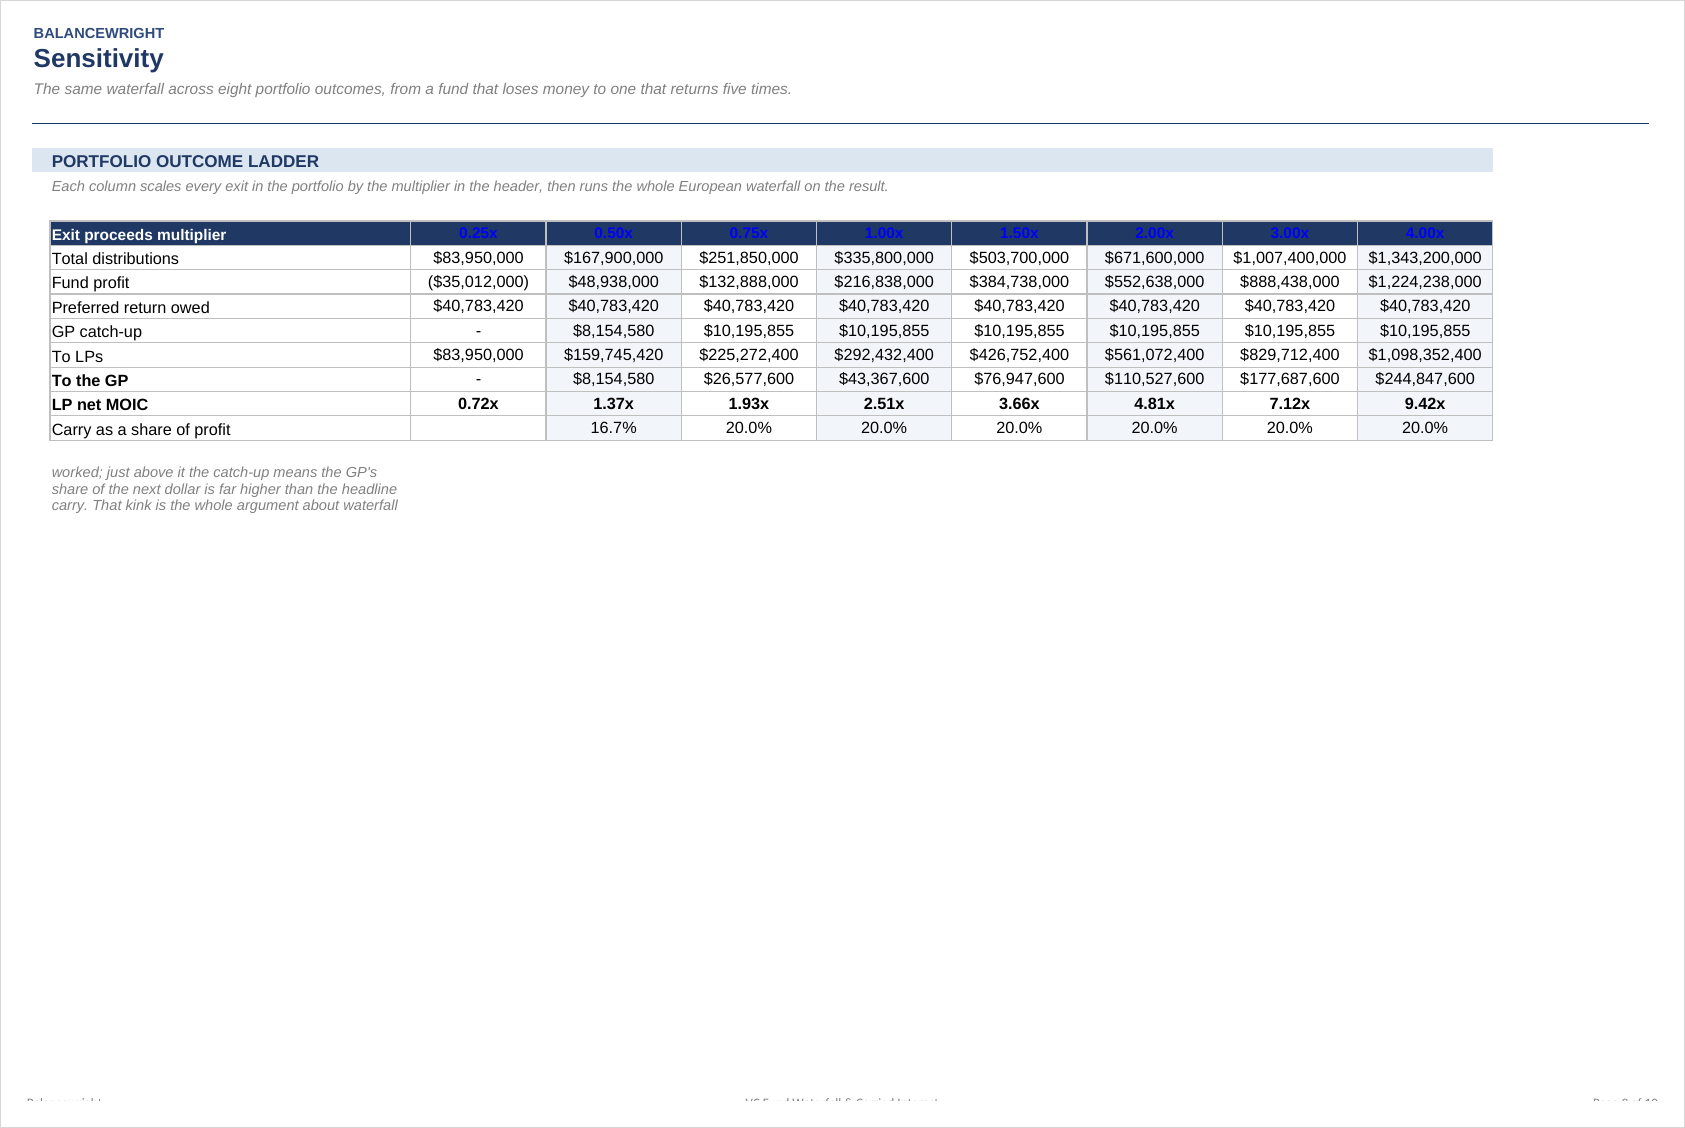
The consequence is a kink. Below the hurdle the GP earns nothing however hard it worked, and just above it the GP's share of the next dollar is far higher than the headline carry. That kink is the whole argument about waterfall terms, and the sensitivity ladder makes it visible as a row of numbers rather than a debate.

EUROPEAN AGAINST AMERICAN, AND THE CLAWBACK
A deal-by-deal American waterfall lets the GP take carry on each profitable exit as it happens, ignoring the losers that have not yet been realised. Over a fund's life that can only ever favour the GP, which is why the model checks that the deal-by-deal figure is at least the whole-fund figure and flags it if it is not.

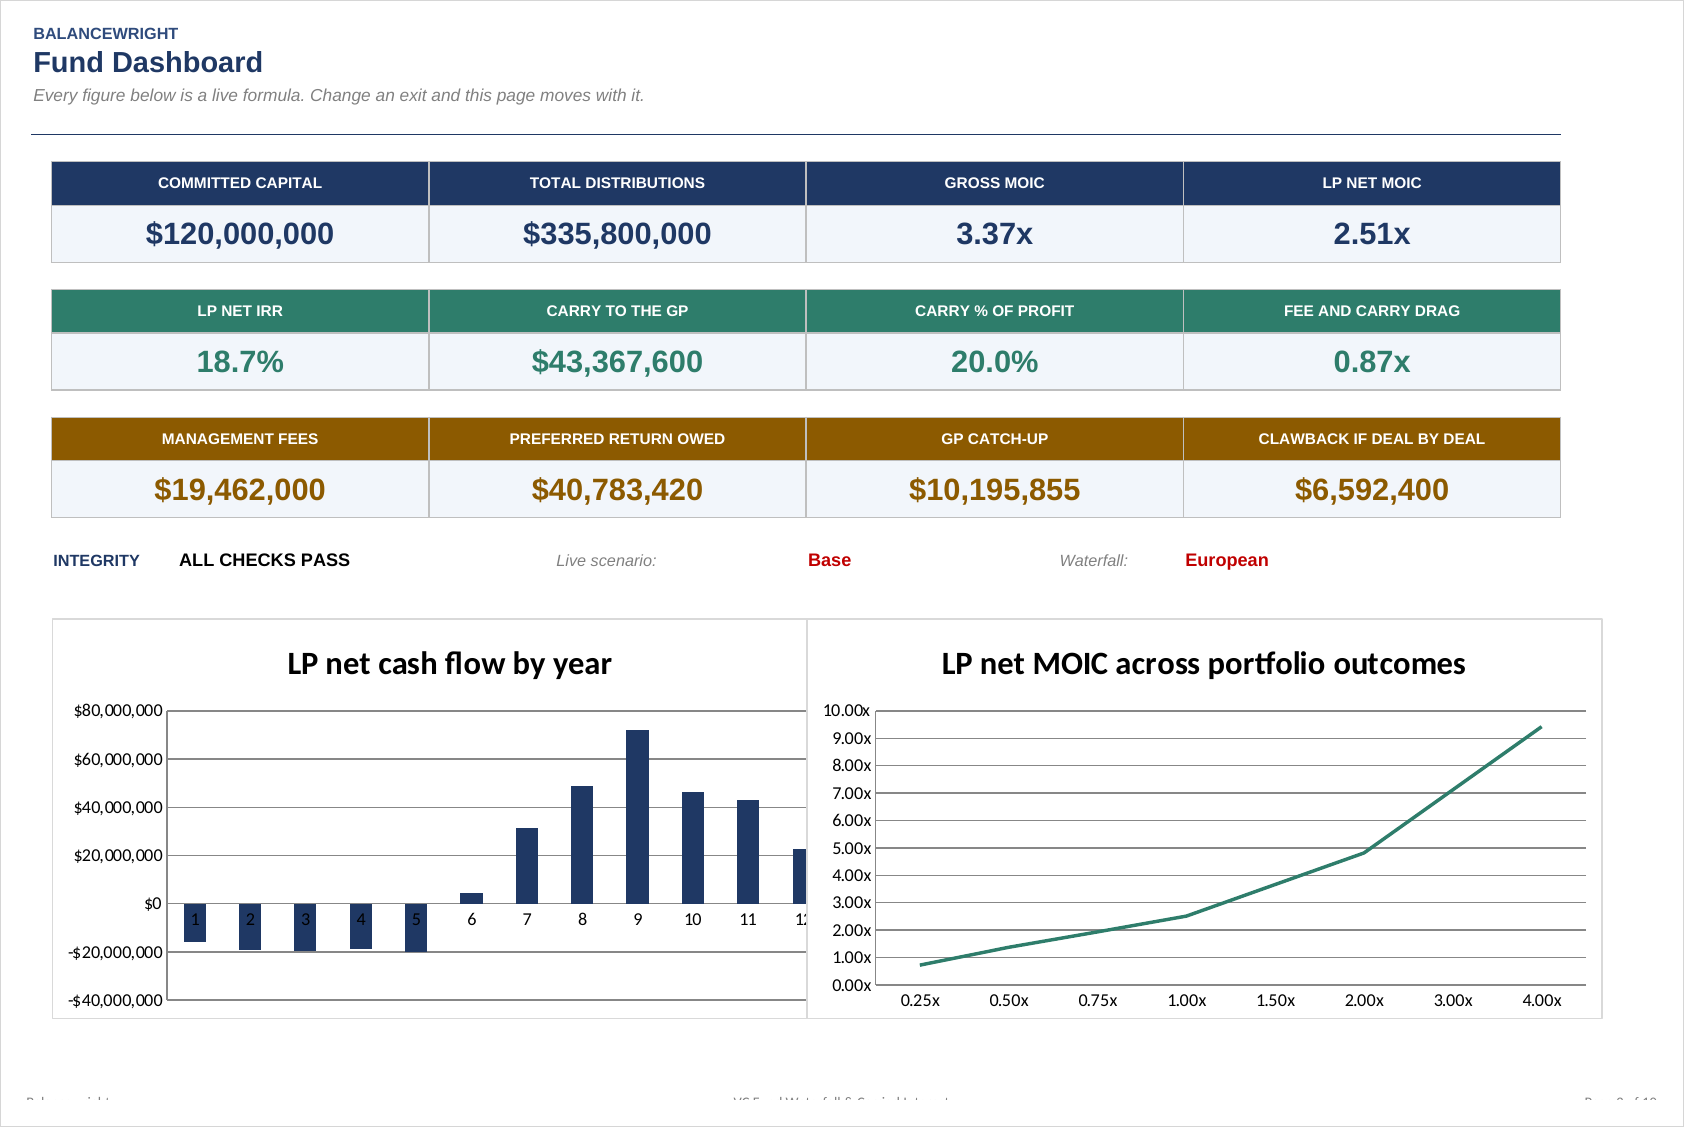
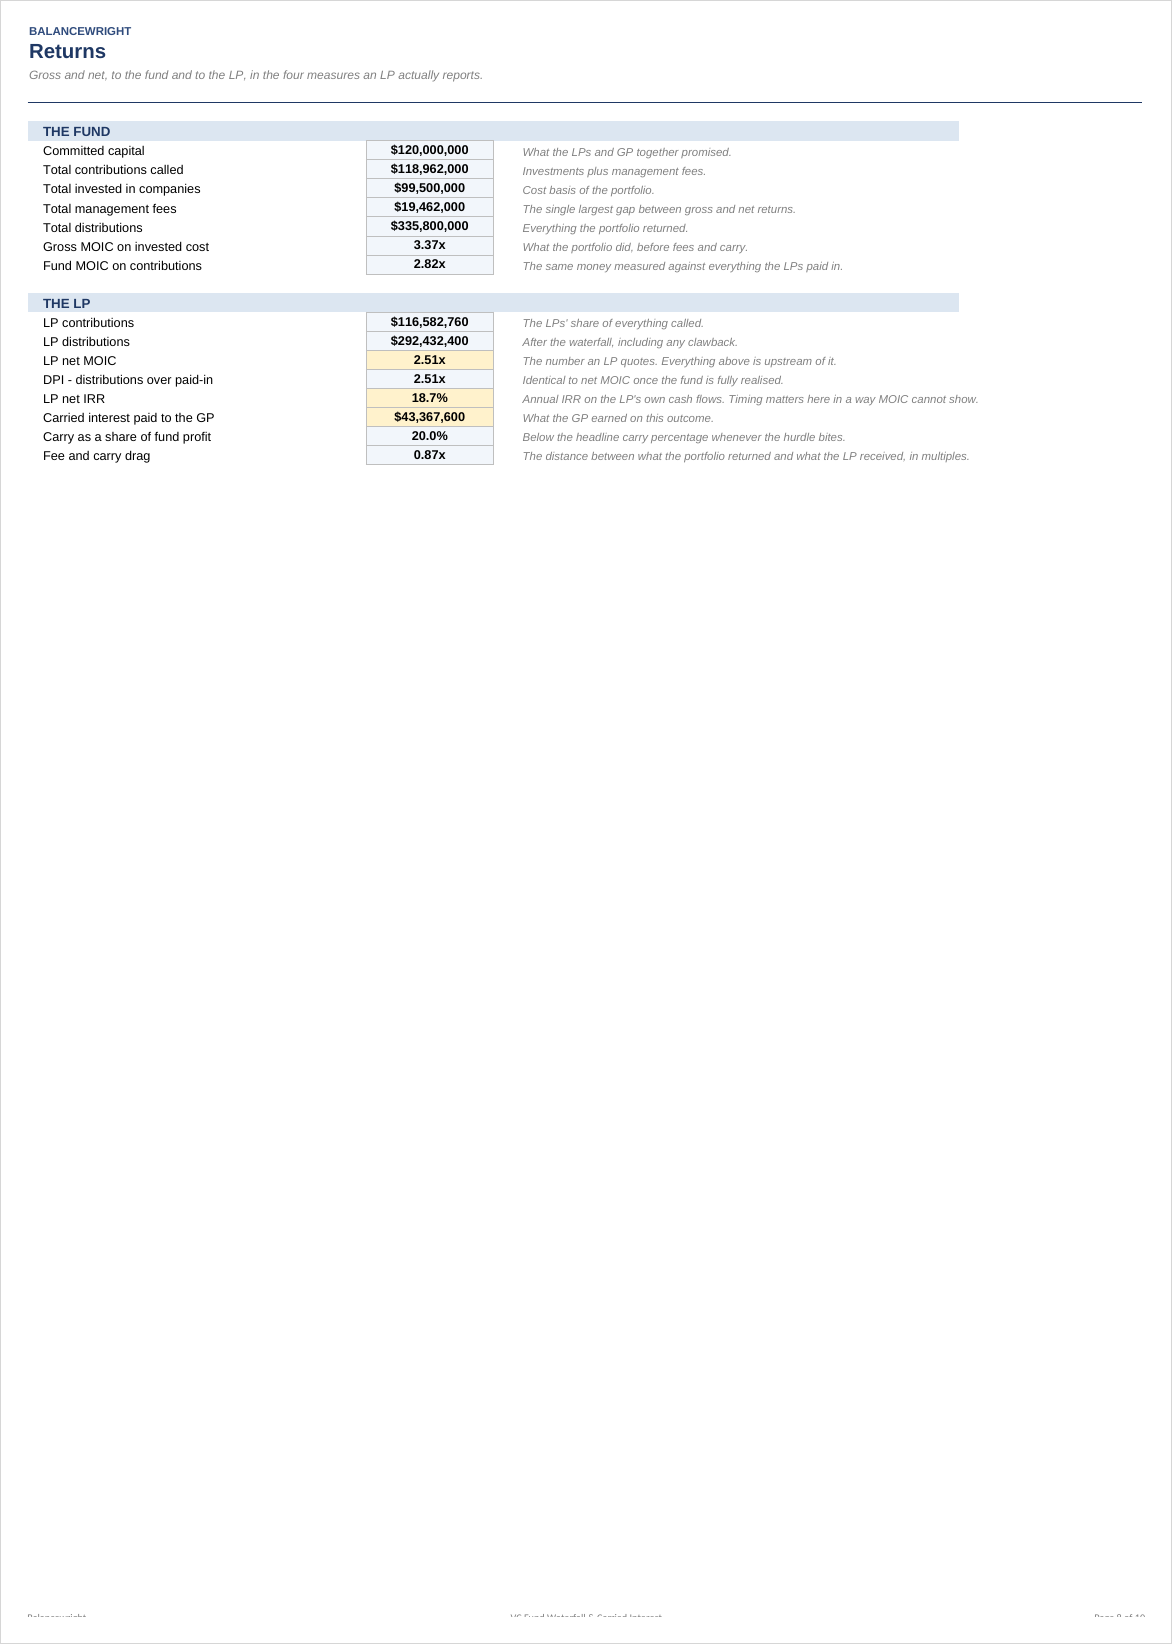
The difference between the two is the clawback: money the GP has already received and, at the end of the fund, owes back. In the worked example a hundred and twenty million dollar fund returning 3.4x gross produces a clawback of roughly 6.6 million. That is not a rounding difference; it is the number an LP negotiates over.

WHAT IS INSIDE
Nine tabs: Read Me, Dashboard, Assumptions, Portfolio, Fund Cash Flows, Waterfall, Returns, Sensitivity, Checks. Twenty-five investments, twelve fund years, three scenarios from one cell.

Management fees are charged on committed capital during the investment period and then on either committed capital or the cost of unrealised investments, whichever basis you choose. Capital calls, fees and distributions build a twelve-year LP cash flow, and the net IRR is computed on that row rather than asserted.
Thirteen integrity checks must all read PASS, including one that confirms contributions fit inside the committed capital, because a fund cannot call more than the LPs promised.

This workbook models the arithmetic of fund terms. It is not investment advice, and the sample portfolio is invented.

This Best Practice includes
1 Excel workbook (9 tabs) and 1 five-page PDF guide.

Acquire business license for $59.00

Add to cart

Add to bookmarks

Discuss

Further information

Understand and negotiate fund economics: what the portfolio returned gross, what the LPs received net, what the GP earned, and how much of the gap is the hurdle, the catch-up and the fee load.

You are an LP modelling what you will actually receive; a GP modelling carry; a fund lawyer or adviser explaining terms; a student or analyst who needs to see a waterfall built rather than described.

You need a multi-fund platform model, GP commitment and co-invest mechanics, management company economics, or fund-level credit facilities. This is one fund, one waterfall.

0.0 / 5 (0 votes)

please wait...