Multifamily Value-Add Apartment Acquisition Model with LTV/DSCR Loan Sizing and Promote Waterfall (Excel)
Originally published: 08/10/2026 14:04
Publication number: ELQ-10614-1
View all versions & Certificate
certified

Multifamily Value-Add Apartment Acquisition Model with LTV/DSCR Loan Sizing and Promote Waterfall (Excel)

Underwrite an apartment value-add deal: the loan sized by all three lender tests, renovation unit by unit, and a four-tier promote waterfall.

Description
This workbook underwrites the purchase, renovation, refinancing and sale of an apartment property over a ten-year hold. Eight tabs, 855 live formulas, one worked example loaded and working the moment you open it.

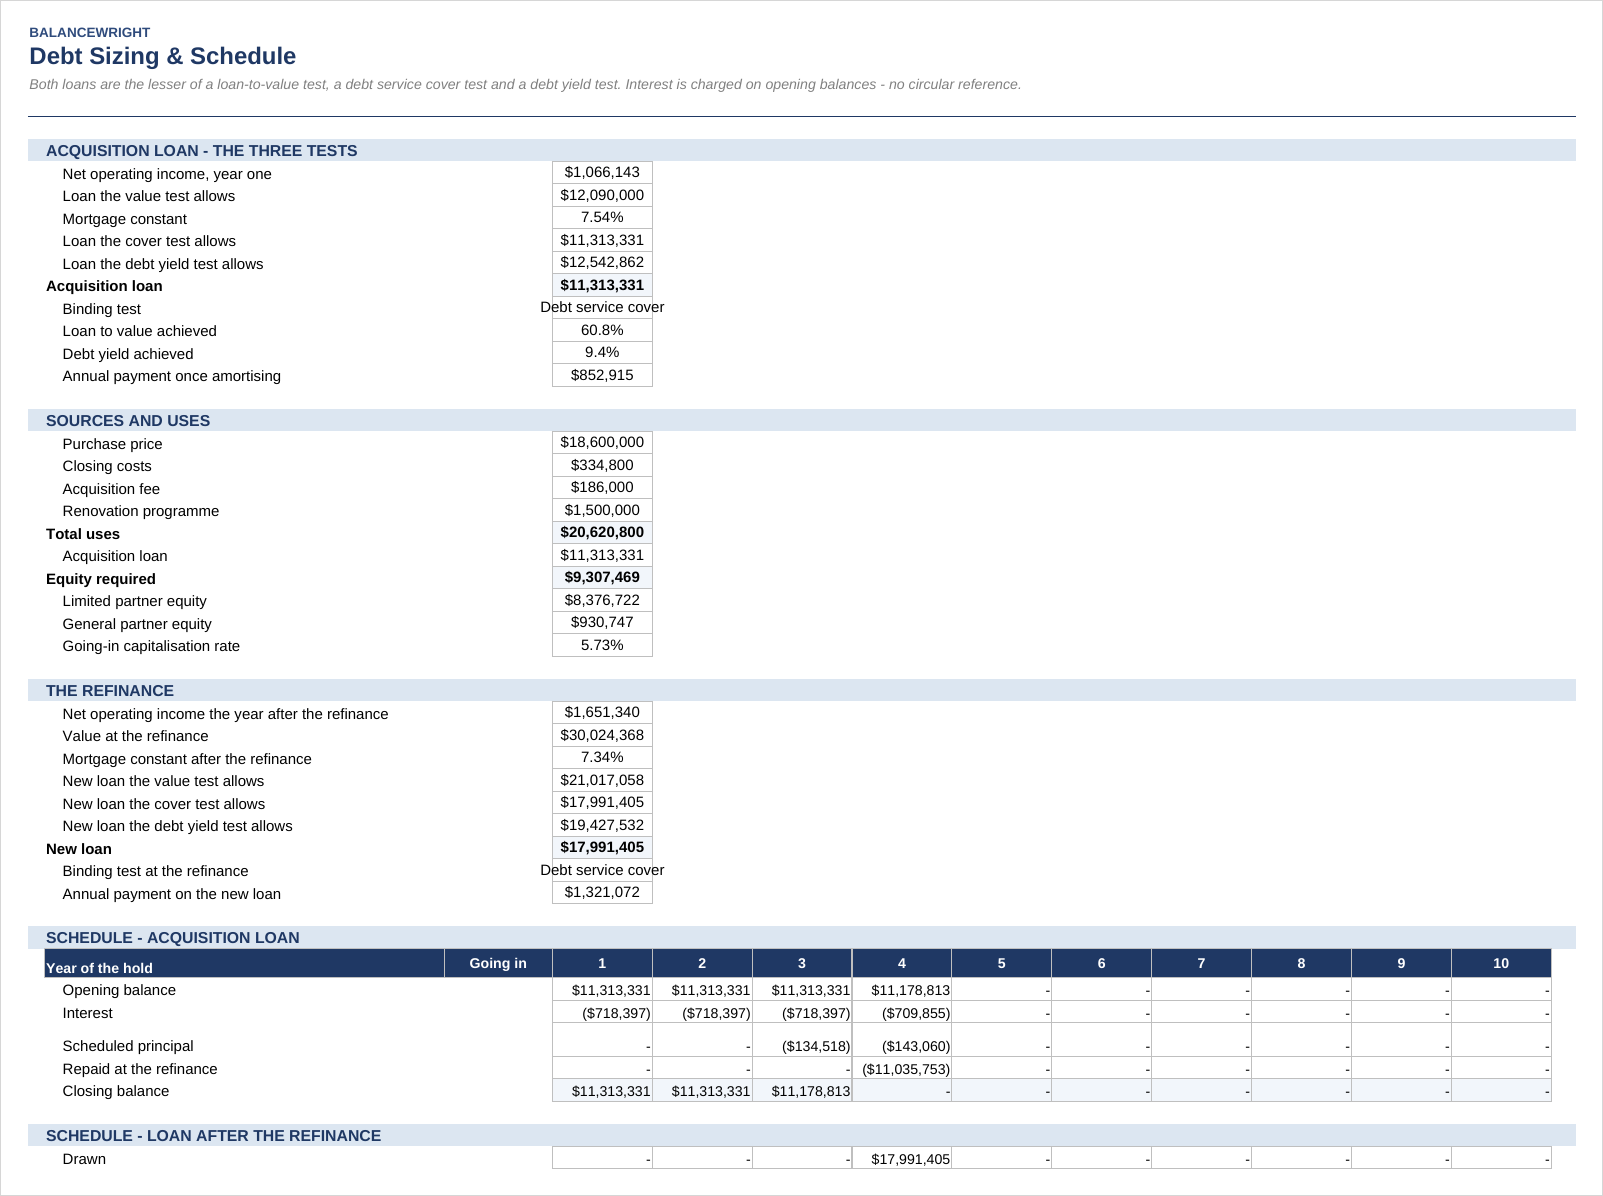
The loan is sized, not typed in. Most value-add templates ask you to enter a loan amount and then report a debt service cover ratio that nothing in the file acts on. Here the loan is the smallest of the three tests a lender actually runs - loan to value, debt service cover and debt yield - solved in closed form through the mortgage constant, and the binding test is named in a cell you can read. In the worked example the value test allows $12.09m, the cover test allows $11.31m and the debt yield test allows $12.54m, so the loan is $11.31m, the binding test is debt service cover, and the 60.8% loan to value that results is a consequence rather than an assumption.

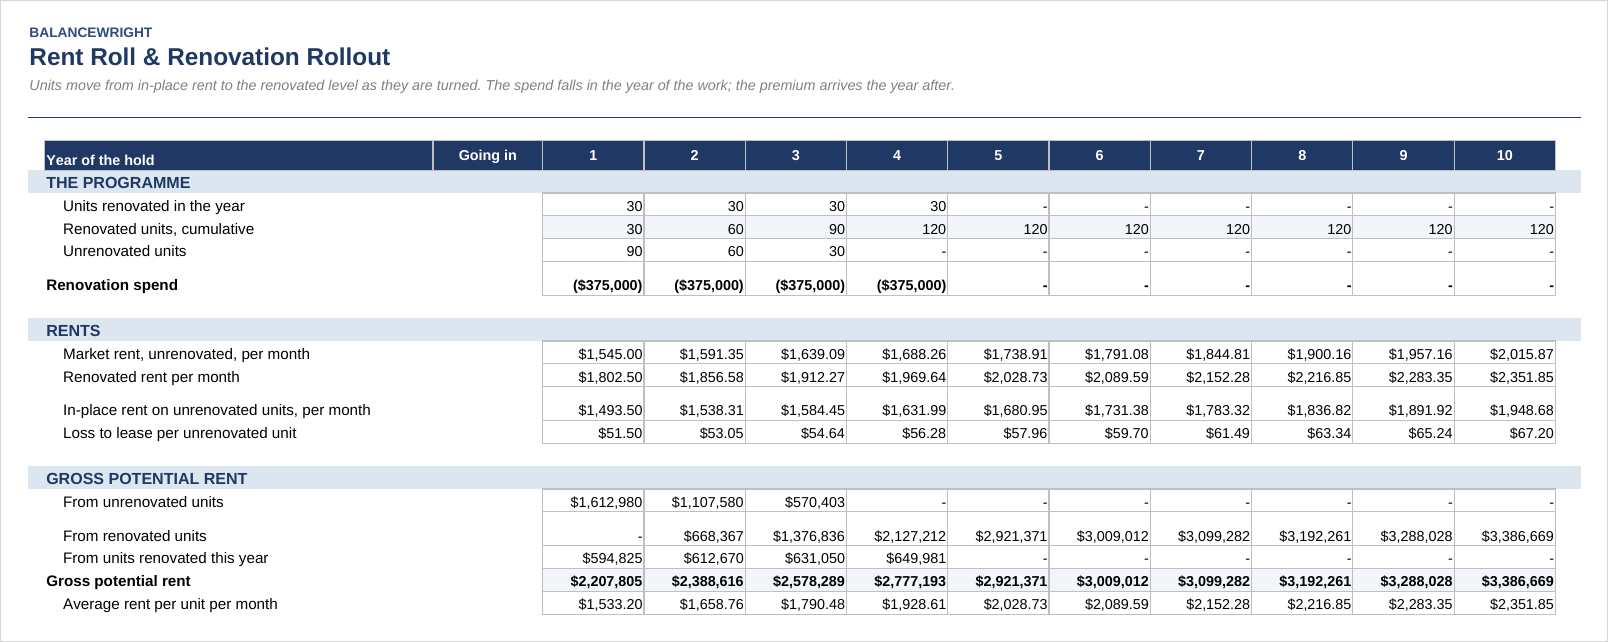
The renovation programme is modelled unit by unit. Thirty units turn a year until the property runs out of units. A unit turned in year three earns the renovated rent for eleven of that year's twelve months and for all twelve of every year after, while the units still waiting earn the in-place rent and carry a loss to lease the model reports on its own line. The programme funds itself from a reserve raised at close, drawn down as the units turn, with anything left released into the sale.

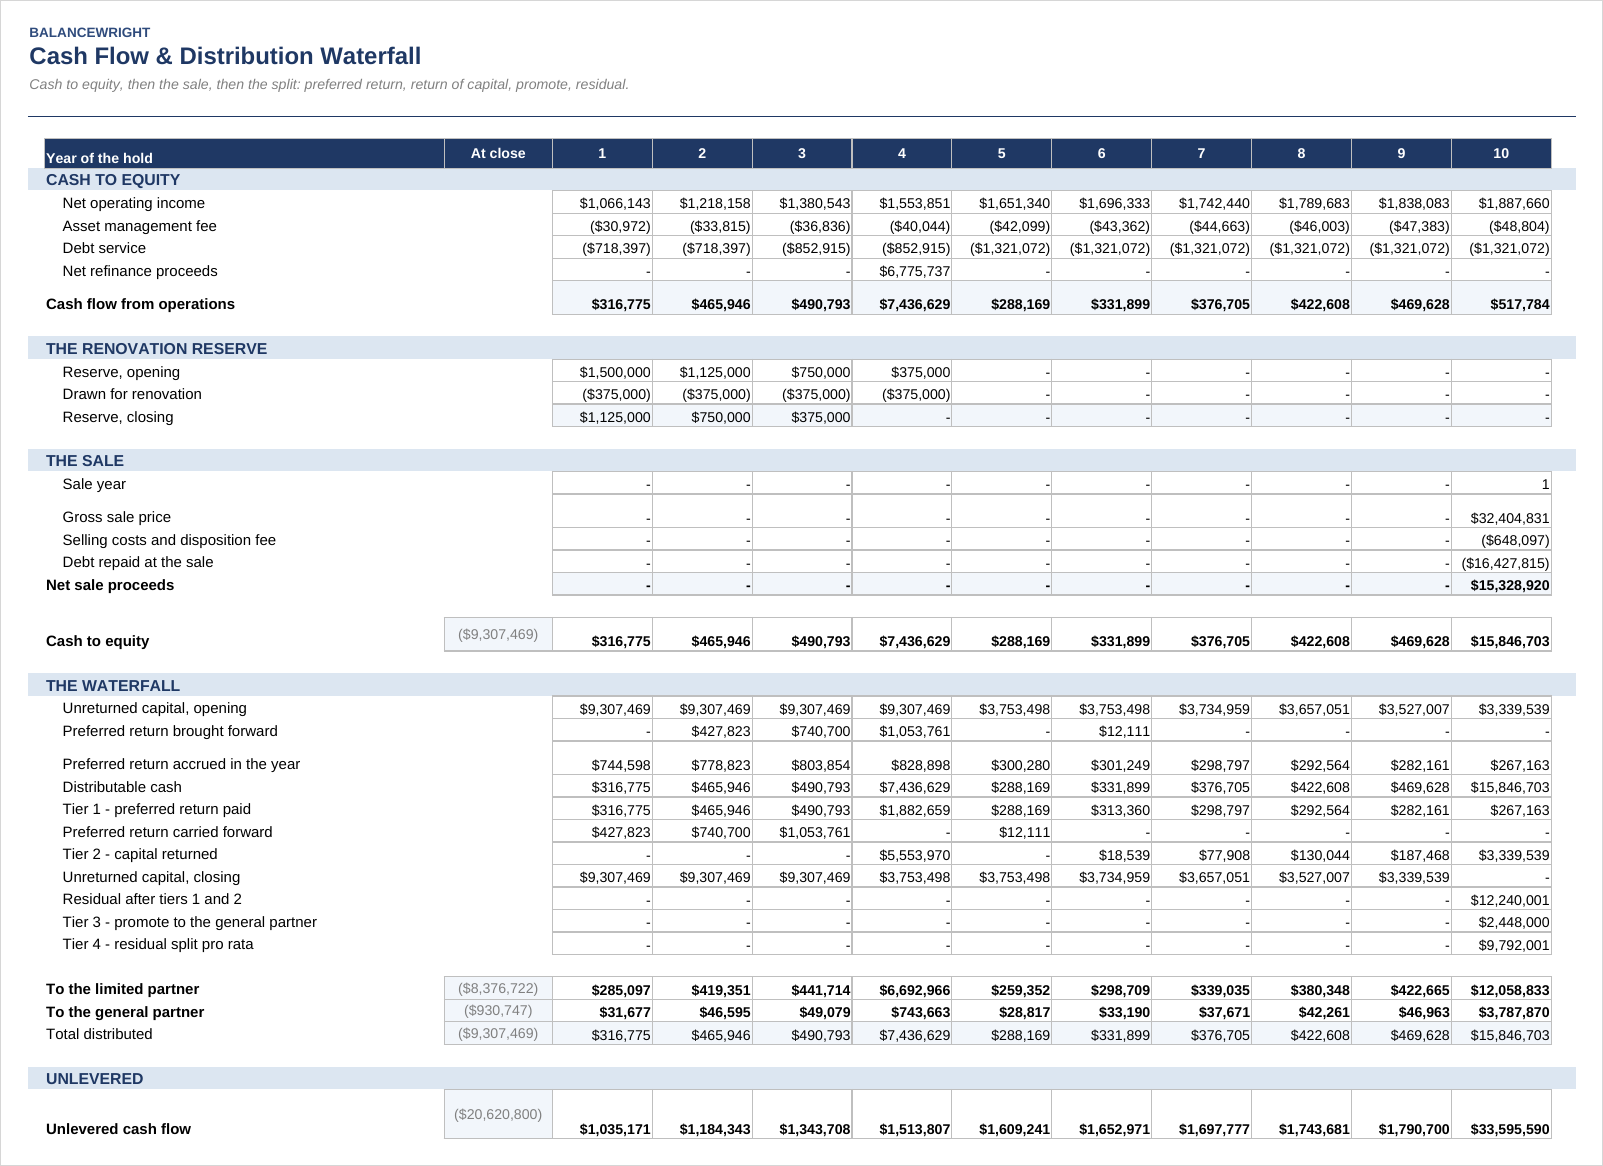
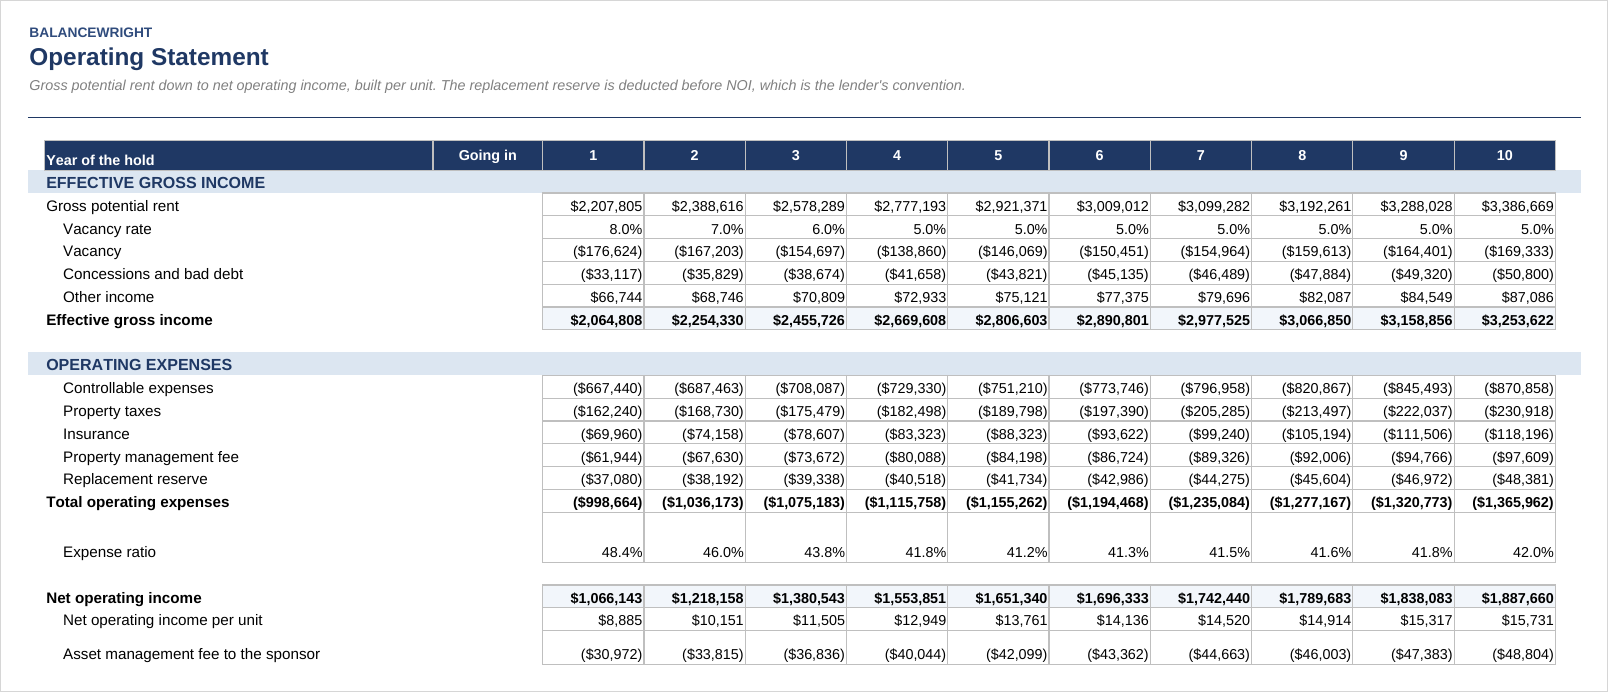
The refinance is sized the same way, against stabilised income. Three tests again, run on the net operating income of the year after the refinance rather than the income at close. In the worked example the property is refinanced in year four at a 5.5% cap rate against $1.65m of NOI, the new loan is $17.99m, and net proceeds of $7.44m return most of the $9.31m of equity in year four.

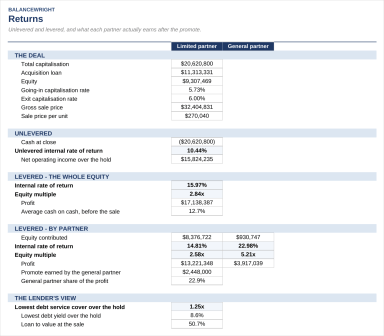
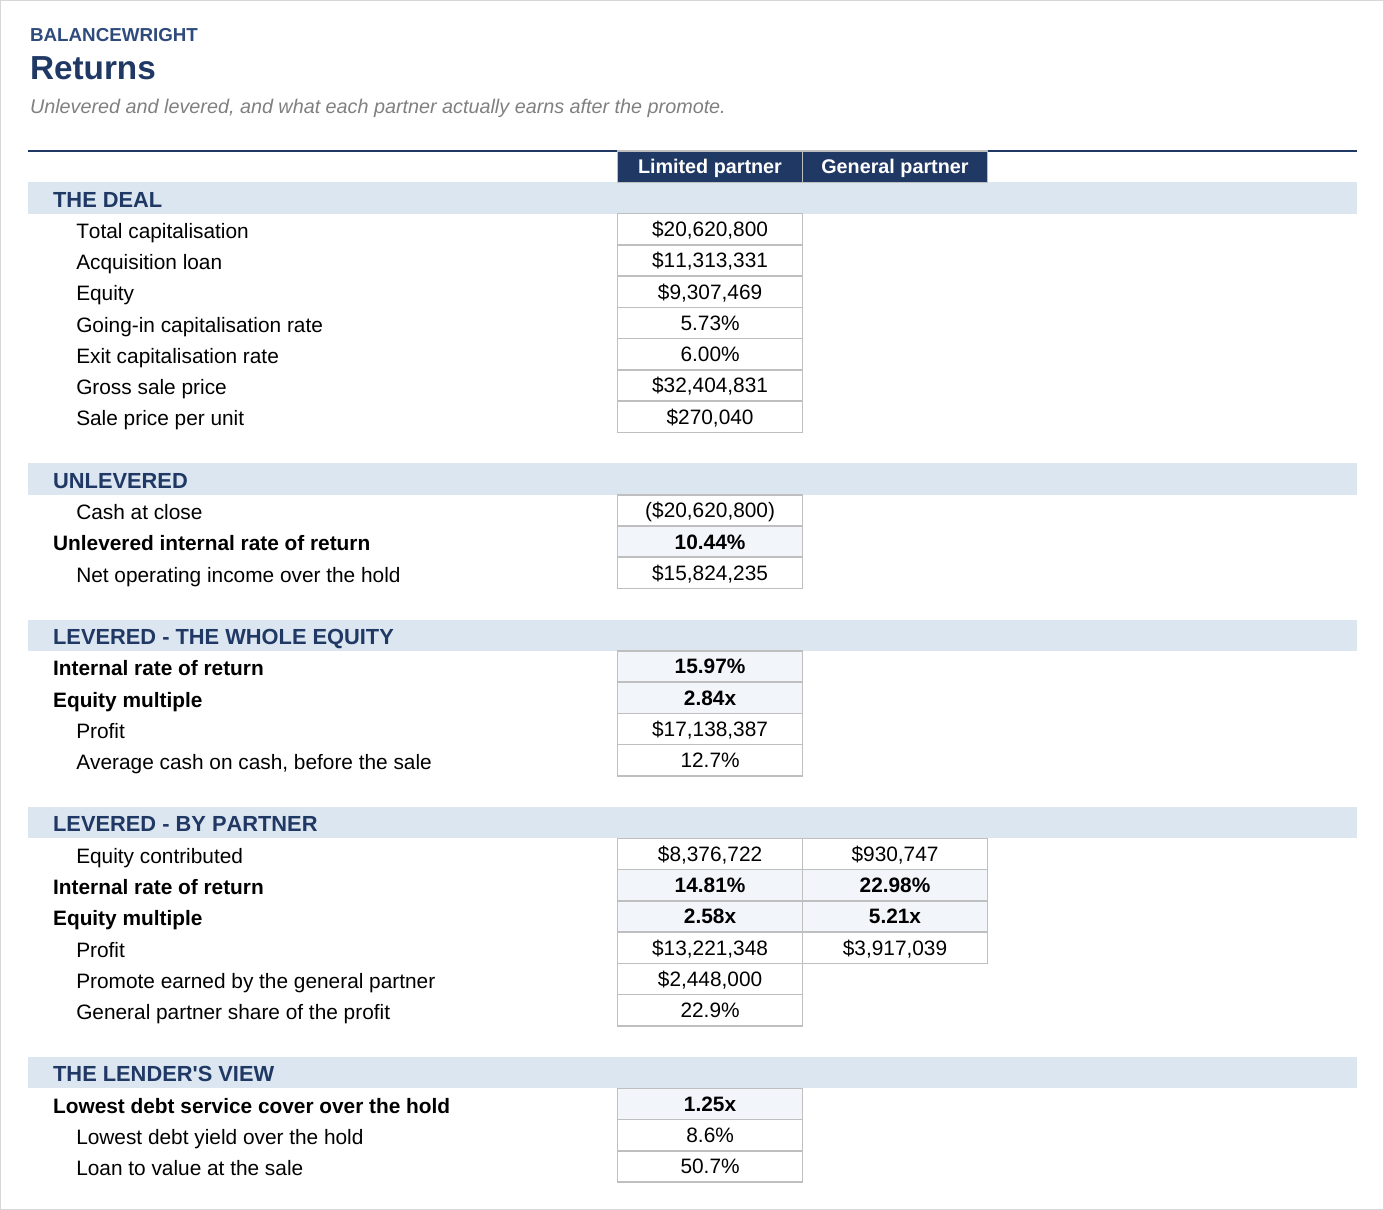
The waterfall shows what the promote costs. Four tiers: a compounding 8% preferred return that accrues on unreturned capital and on preferred return that went unpaid, then return of capital, then a 20% promote on the residual, then a pro rata split. The whole equity earns 15.97% and 2.84x. The limited partner earns 14.81% and 2.58x. The general partner takes 22.9% of the profit on 10% of the equity. All three numbers sit next to each other on the Returns tab.

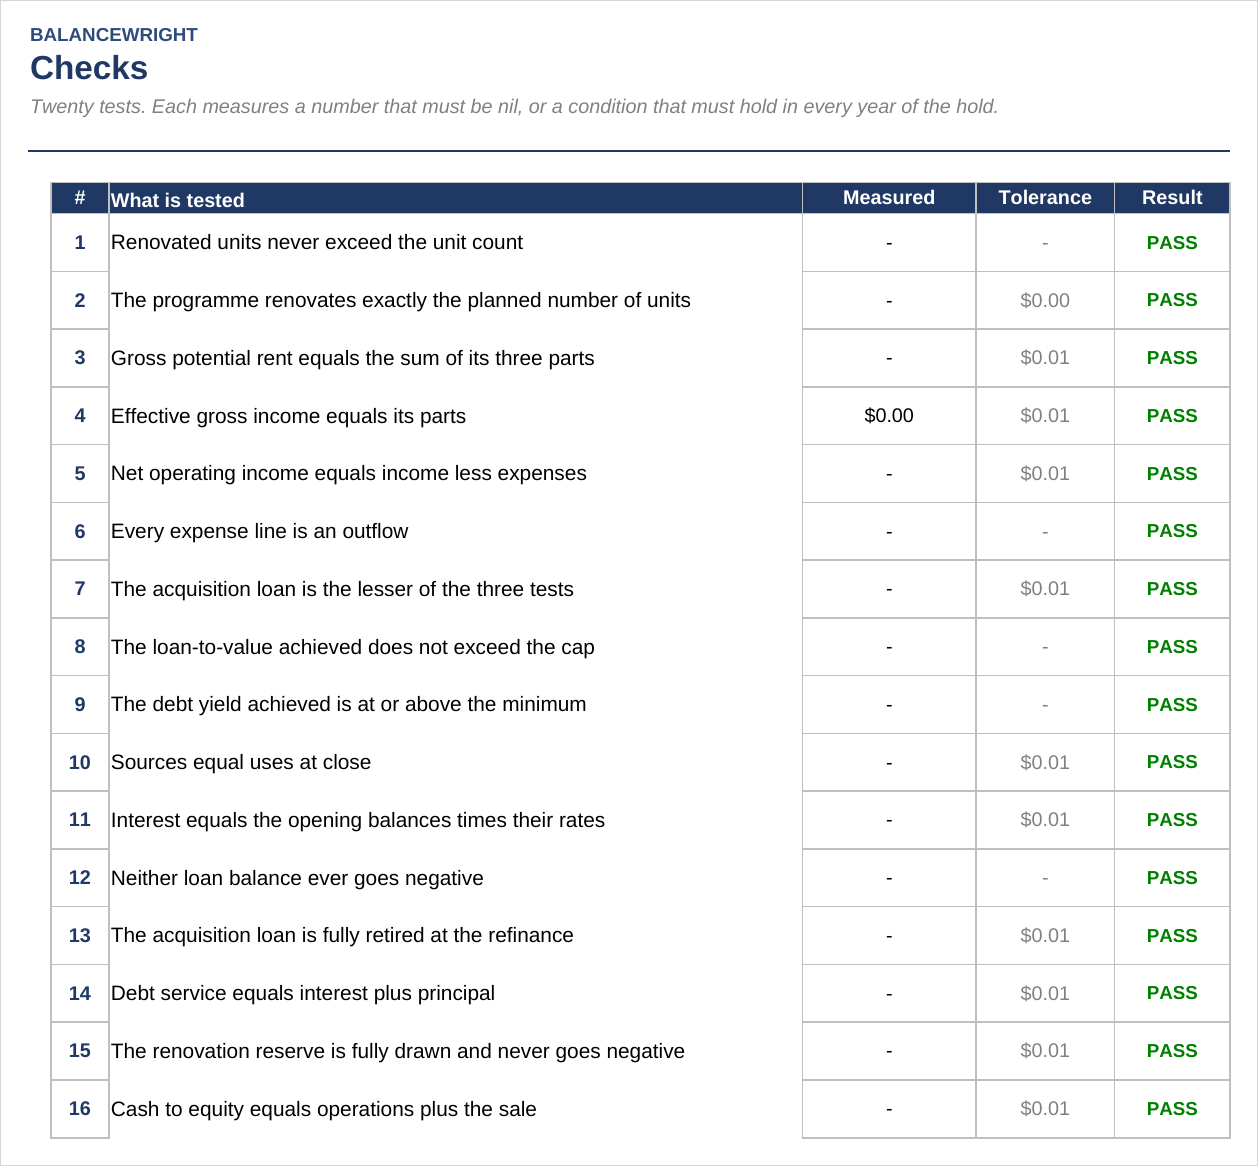
Twenty checks. Each measures a number that must be nil or a condition that must hold in every year: the programme never renovates more units than the property has, gross potential rent equals the sum of its three parts, the loan equals the smallest of the three tests, sources equal uses, the waterfall distributes exactly the cash available, and capital and preferred return are both fully settled by the end of the hold.

Tabs: Read Me, Assumptions, Rent Roll & Renovation, Operating, Debt, Cash Flow & Waterfall, Returns, Checks.

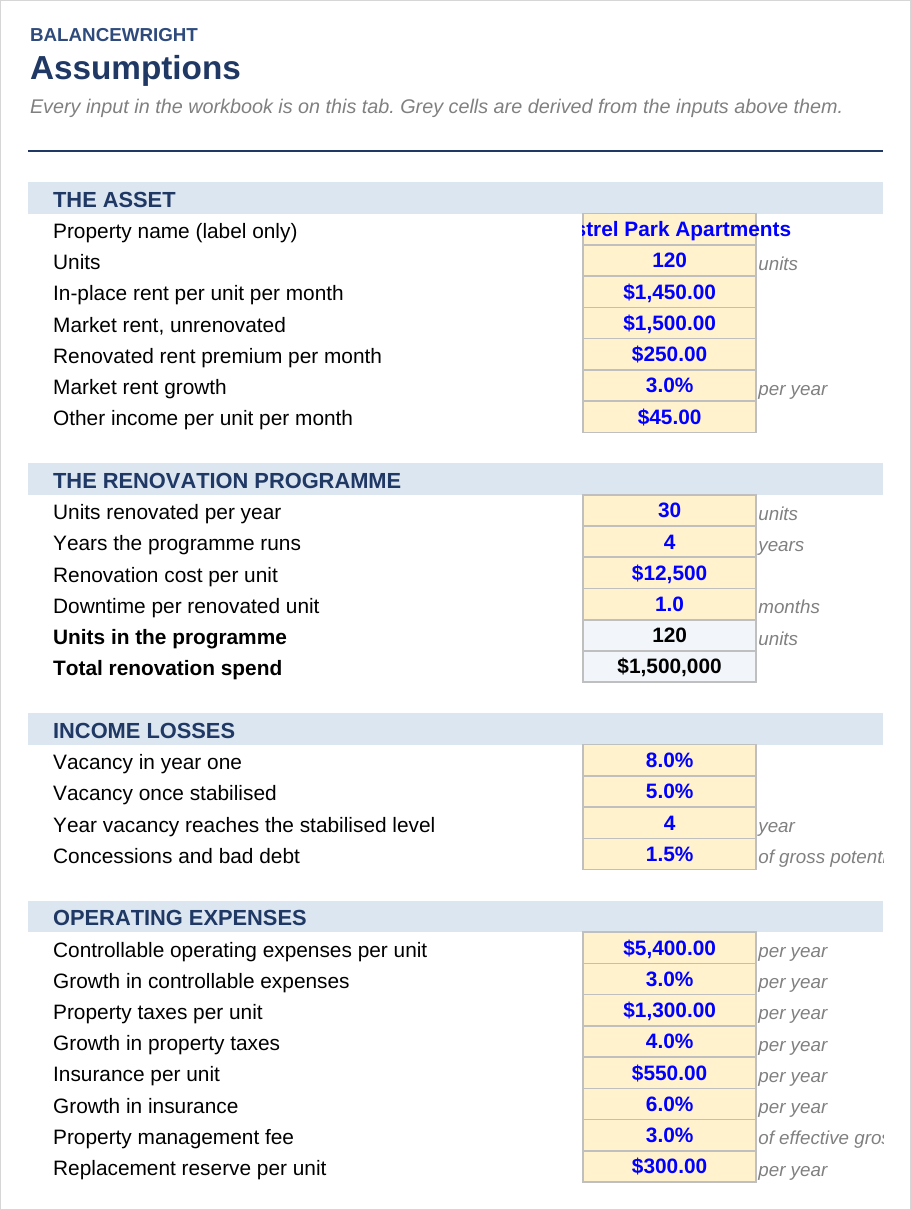
Worked example. Kestrel Park Apartments - 120 units at $18.6m, in-place rent $1,450 against a $1,500 market, a $250 renovated premium, 30 units a year for four years at $12,500 each, refinanced in year four, sold in year ten at a 6.0% exit cap for $32.4m, or $270,040 a unit. Going-in cap 5.73%, unlevered IRR 10.44%, levered IRR 15.97%, average cash on cash 12.7%, lowest debt service cover 1.25x.

How it is built. Microsoft Excel (.xlsx). No macros, no add-ins, no external links, no password protection, no locked cells, and iterative calculation off - interest is charged on opening balances, so the whole financing block resolves left to right in one pass and returns the same numbers in Excel, LibreOffice, Numbers and Google Sheets.

Every figure was independently re-derived before publication: the whole deal was rebuilt in a second implementation and compared to the workbook in 129 separate tests, with both internal rates of return solved by bisection rather than by Excel's IRR. A 12-page guide and preview PDF is included with the download.

This Best Practice includes
One Excel workbook (.xlsx) with eight tabs and 855 live formulas, plus a 12-page guide and preview PDF

Acquire business license for $79.00

Add to cart

Add to bookmarks

Discuss

Further information

Underwrite the purchase, renovation, refinancing and sale of an apartment property over a ten-year hold, with the loan sized by the lender’s own three tests rather than typed in, and the promote split shown partner by partner.

You are underwriting a value-add multifamily acquisition, negotiating loan terms with a lender, raising equity on a preferred-return-and-promote structure, or checking a sponsor’s numbers before you invest.

You need a monthly construction draw schedule, a portfolio roll-up, US tax and depreciation, or a ground-up development. This model is annual, single-property and pre-tax.

0.0 / 5 (0 votes)

please wait...